Retainer vs Token Loan: How Crypto Market Making Deals Are Actually Structured
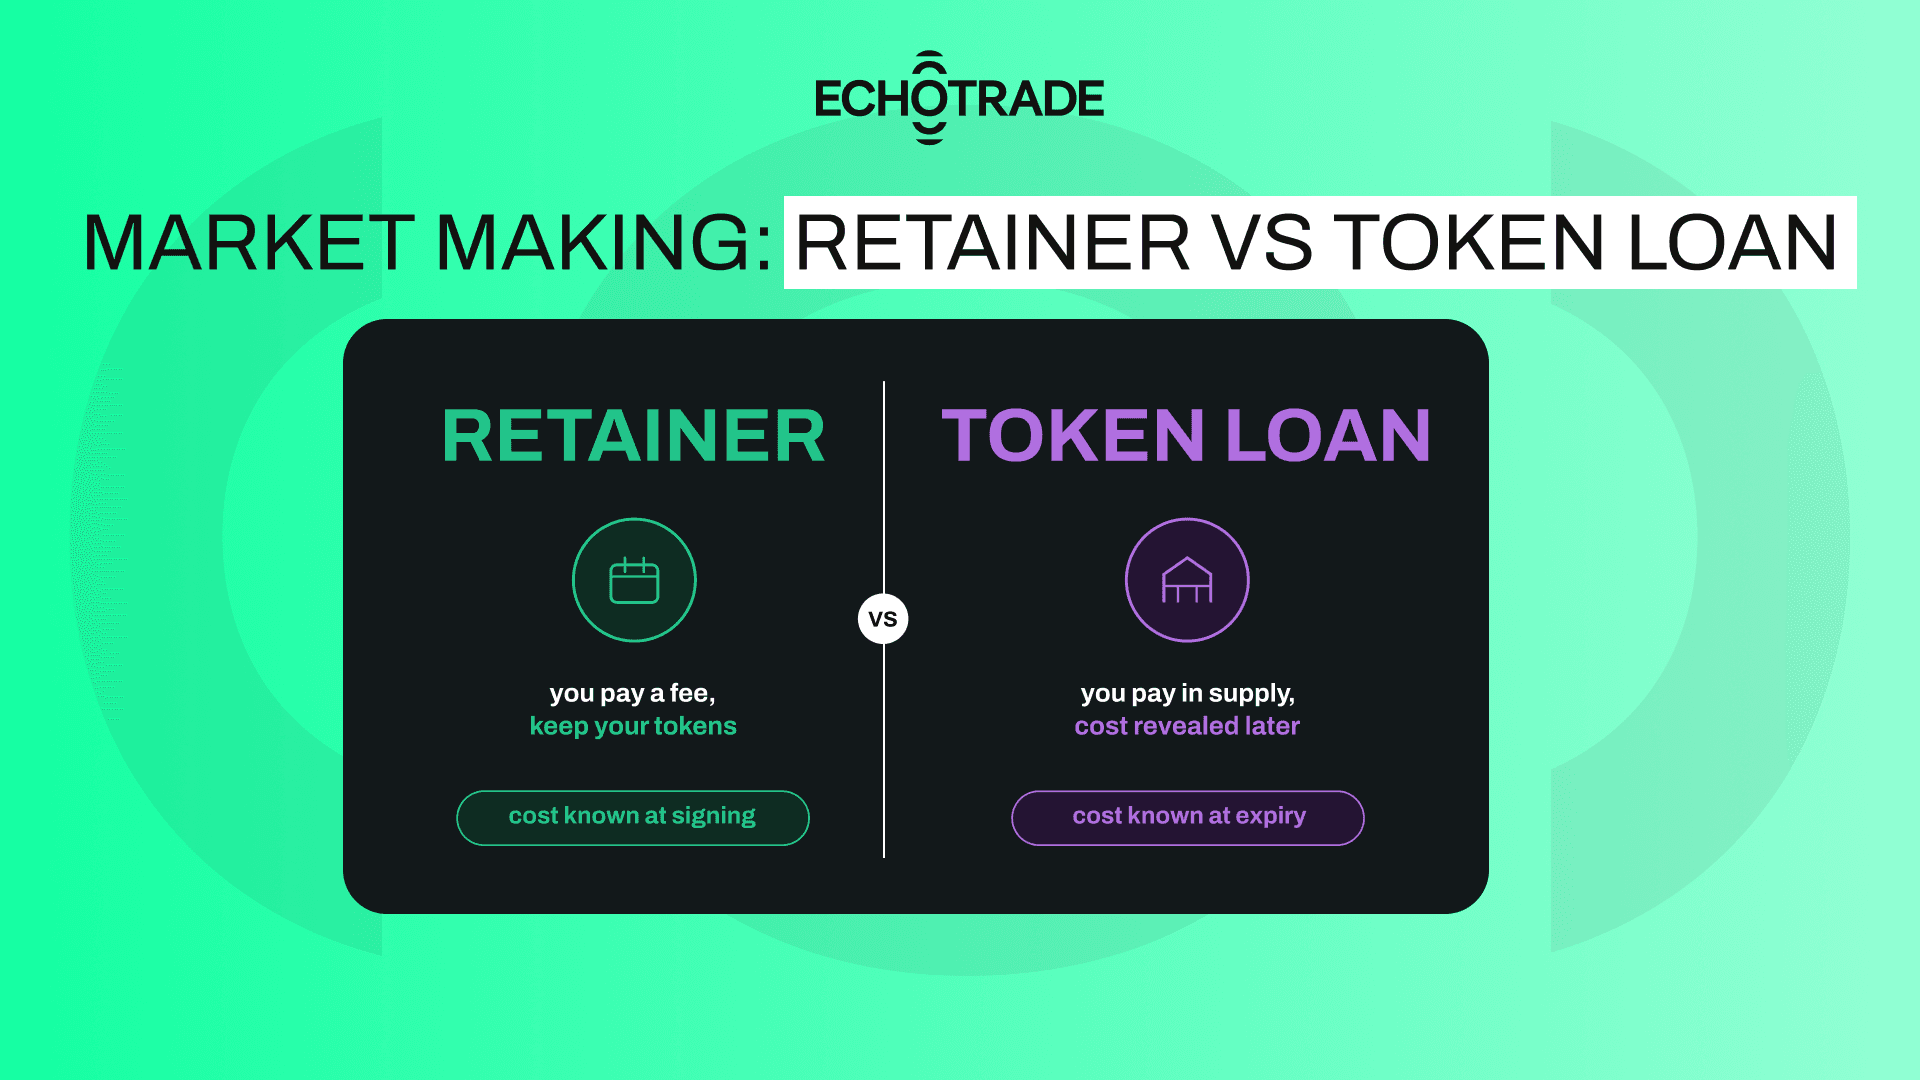
A token loan of 1% of supply sounds cheaper than a $10,000 monthly retainer. Depending on how your token performs, it can cost fifty times more.
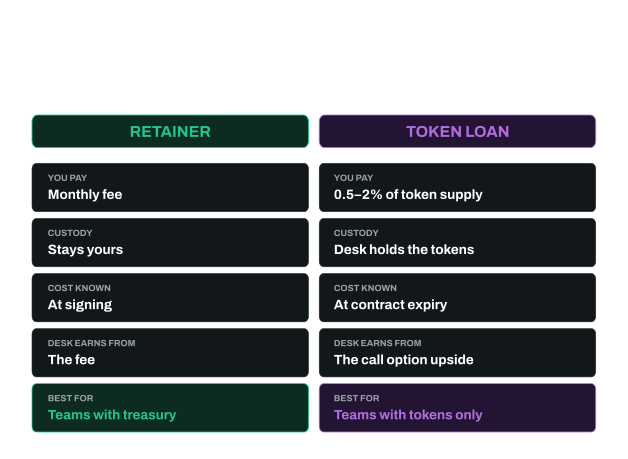
The short version: crypto market making is priced through two structures. In a retainer model, the project pays a monthly fee, provides the trading capital, and keeps custody of its tokens. In a token loan model, the desk borrows 0.5% to 2% of token supply, trades with its own stablecoins, charges little or no monthly fee, and typically holds an option to repay the loan in tokens or in dollars at a preset price. Both are legitimate. They distribute cost, risk and incentives completely differently, and most launch-stage problems with market makers trace back to a team signing one model while imagining the other.
Full disclosure before the comparison: EchoTrade works on the retainer model. We think the reasoning below is fair to both structures, and we would rather you understand the trade than take our word for it.
How the retainer model works
The project pays a fixed monthly fee for a defined scope: which exchanges, what depth, what spread targets, what uptime. The project supplies the working capital the desk quotes with, and that capital stays the project's property throughout.
Pros:
Full custody. Your tokens and your capital remain yours. The engagement ends, everything comes home.
Transparent cost. The fee is the fee. You can budget it for the year and compare quotes between desks directly.
Aligned incentives. The desk earns the same whether your price rises or falls, so its job is simply to keep the book healthy. There is no scenario where your market maker profits from your token's decline.
Clean reporting. Because the capital is yours, you see what it is doing: depth, spreads, uptime against the agreed KPIs.
Cons:
Cash cost from day one. Typical retainers run from a few thousand to $20,000+ per month depending on venue count, and the working capital comes on top. For a team with tokens but little cash, this is the hard constraint. If you want the full price ranges behind these numbers, we published them in how much a crypto market maker costs.
Capital requirement. The project funds the inventory, commonly $50,000 to $1M+ depending on venues and depth targets. Under heavy selling, that inventory absorbs the pressure and may need topping up.
Scope discipline required. A fixed fee means a fixed scope. Add exchanges later and the fee grows with them.
How the token loan model works
The desk borrows a slice of token supply, typically 0.5% to 2%, and provides liquidity using its own stablecoins on the other side. Instead of a fee, the deal includes an option: at the end of the term, usually 12 to 24 months, the desk chooses whether to return the tokens or keep them and pay a preset dollar price.
Pros:
Little or no cash outlay. For a pre-revenue team whose only asset is its token, this can be the difference between having a market maker and not having one.
The desk brings capital. Its stablecoins fund the other side of the book, so the project's treasury is not tied up in exchange accounts.
Simple to sign. No monthly invoicing, no working capital transfers. One agreement, one transfer of tokens.
Cons:
The real cost is invisible at signing. The option is the payment. If your token performs well, the desk exercises the option cheaply and keeps the upside on 0.5% to 2% of your supply. Strong performance is exactly when the deal turns expensive.
Incentives can diverge. A desk holding your tokens plus an option has views about your price. Most loan-model desks behave professionally. But the structure itself creates scenarios where the desk's best outcome is not your best outcome, and you are trusting behavior rather than structure.
Supply overhang. 1-2% of supply sitting with a trading firm is a position the market may eventually learn about. Sophisticated buyers ask who holds what.
Terms hide in the details. Strike price, expiry, repayment currency choice, what happens on a delisting. Loan deals are where founders most often sign something they have not fully modeled.
Which model EchoTrade uses. We operate on a retainer only. We do not take token loans, call options, or profit share, and we never take custody of a project's tokens. The loan model is described here because it is common in the industry and founders need to understand it before signing, not because we offer it.
The honest decision rule
If the project has cash or stablecoin treasury: retainer, almost always. You pay a known price for a known service and keep your supply intact.
If the project has no cash at all: the loan model exists precisely for you, and it can be the right call, entered with open eyes. Model the option's cost at three scenarios (token at half price, flat, and 3x), get the strike and expiry in writing, and have someone independent read the agreement.
If a desk offers only one model and will not discuss the structure of it in plain terms, that is information too.
What healthy depth, spread and uptime actually look like once either deal is live is the subject of our full guide to crypto market making.
FAQ
Which is cheaper, a retainer or a token loan?
At signing, the token loan almost always looks cheaper because there is no invoice. Over the life of the deal, it depends entirely on token performance: if the token appreciates, the option the desk holds can make the loan model several times more expensive than a retainer would have been. The retainer's cost is fixed and knowable; the loan's cost is variable and realized later.
What percentage of token supply do market makers borrow?
Typically 0.5% to 2% of total supply, on terms of 12 to 24 months. Larger allocations should prompt questions: the loan exists to fund order books, and healthy books rarely require more than this range.
Do market makers return borrowed tokens?
Under a loan-plus-option structure, the desk chooses at expiry: return the tokens, or keep them and pay the agreed strike price. Whether tokens come back depends on where the market price sits relative to that strike. This choice belongs to the desk, not the project, which is the single most misunderstood term in these agreements.
Can a project switch models mid-engagement?
Usually only at renewal. Loan agreements in particular run to fixed expiry because the option is the desk's compensation. This is why modeling the deal before signing matters more in the loan model: you cannot unwind it early without negotiation.
Why do some desks only offer the loan model?
Because it can be significantly more profitable for the desk than a fee, and because it filters for early-stage projects with tokens but no cash. It is a business model choice, not misconduct. The practical takeaway for a founder is to ask any desk which models it offers and why, and to be cautious when the structure of the deal resists plain explanation.
Planning a listing?
We handle the market structure side: order book depth, spreads and uptime across 90+ exchanges. Message us on Telegram before you submit the application, not after.